As fall approaches, so does Medicare Open Enrollment. This vital period, known as the Annual Enrollment Period (AEP), is your yearly chance to review and adjust your Medicare coverage to ensure it still meets your unique health and financial needs. Many find this time overwhelming, wondering if action is truly necessary.
Your current plan might automatically renew, but its benefits, costs, and provider networks can change annually. Your own health needs, medications, or financial situation may have also shifted. Failing to review options could mean missing better benefits or incurring unexpected costs.
This guide will walk you through everything about the upcoming Medicare Open Enrollment. We'll cover key dates, important changes, and practical steps to prepare. You'll gain confidence to make informed decisions about your Medicare coverage, ensuring peace of mind for the year ahead.
Key Takeaways
- Medicare Open Enrollment (AEP) runs from October 15th to December 7th each year. This is your primary opportunity to make changes to your Medicare Advantage and Prescription Drug Plans for the upcoming year.
- Reviewing your plan annually is crucial. Even if you're happy with your current plan, benefits, costs, and provider networks can change, and your health needs might have evolved.
- You can switch Medicare Advantage plans, change from Original Medicare to Medicare Advantage, or vice versa. You can also enroll in, switch, or drop a Prescription Drug Plan (Part D).
- Preparation is key. Gather your current plan details, medication lists, and a summary of your health needs before October 15th to make the review process smoother.
- Independent agents offer free, unbiased help. We can compare plans from multiple carriers, explain complex rules, and help you find a plan that aligns with your specific situation.
What is Medicare Open Enrollment (AEP)?
Medicare Open Enrollment, or the Annual Enrollment Period (AEP), is a specific time each year for individuals with Medicare to change their health and prescription drug coverage for the following calendar year. It’s a critical window to align your Medicare choices with your current health, finances, and provider preferences.
The AEP runs annually from October 15th to December 7th. Any changes made take effect on January 1st. This period differs from your Initial Enrollment Period (IEP) or Special Enrollment Periods (SEPs).
Why is Open Enrollment So Important?
Medicare plans and your circumstances are dynamic. Ignoring Open Enrollment could lead to unexpected costs, coverage gaps, or an unsuitable plan.
Key reasons to review during AEP:
- Annual Plan Changes: Medicare Advantage (Part C) and Prescription Drug Plans (Part D) frequently alter benefits, costs, networks, and drug formularies. Your ideal plan last year may no longer be.
- Changes to Your Health: New diagnoses, doctors, or medications mean your current plan might not cover preferred providers or prescriptions.
- Budget Shifts: A change in financial situation might make a different plan structure more appealing, or affect IRMAA eligibility.
- New Options: New plans with improved benefits, lower costs, or broader networks may become available in your area.
- Prescription Drug Coverage: Formularies change. Ensure your medications are still covered affordably to avoid high drug expenses.
Active participation empowers you to adapt and secure optimal coverage.
Who Should Review Their Medicare Plan During AEP?
Everyone on Medicare should review their plan. Even if content, a quick check confirms you’re still in the best possible plan.
Consider these scenarios:
- Medicare Advantage Plan (Part C) Holders: Your plan’s benefits, network, or costs may change. AEP allows finding better coverage.
- Medicare Part D Prescription Drug Plan Holders: Formularies change annually. Ensure your medications are still covered affordably.
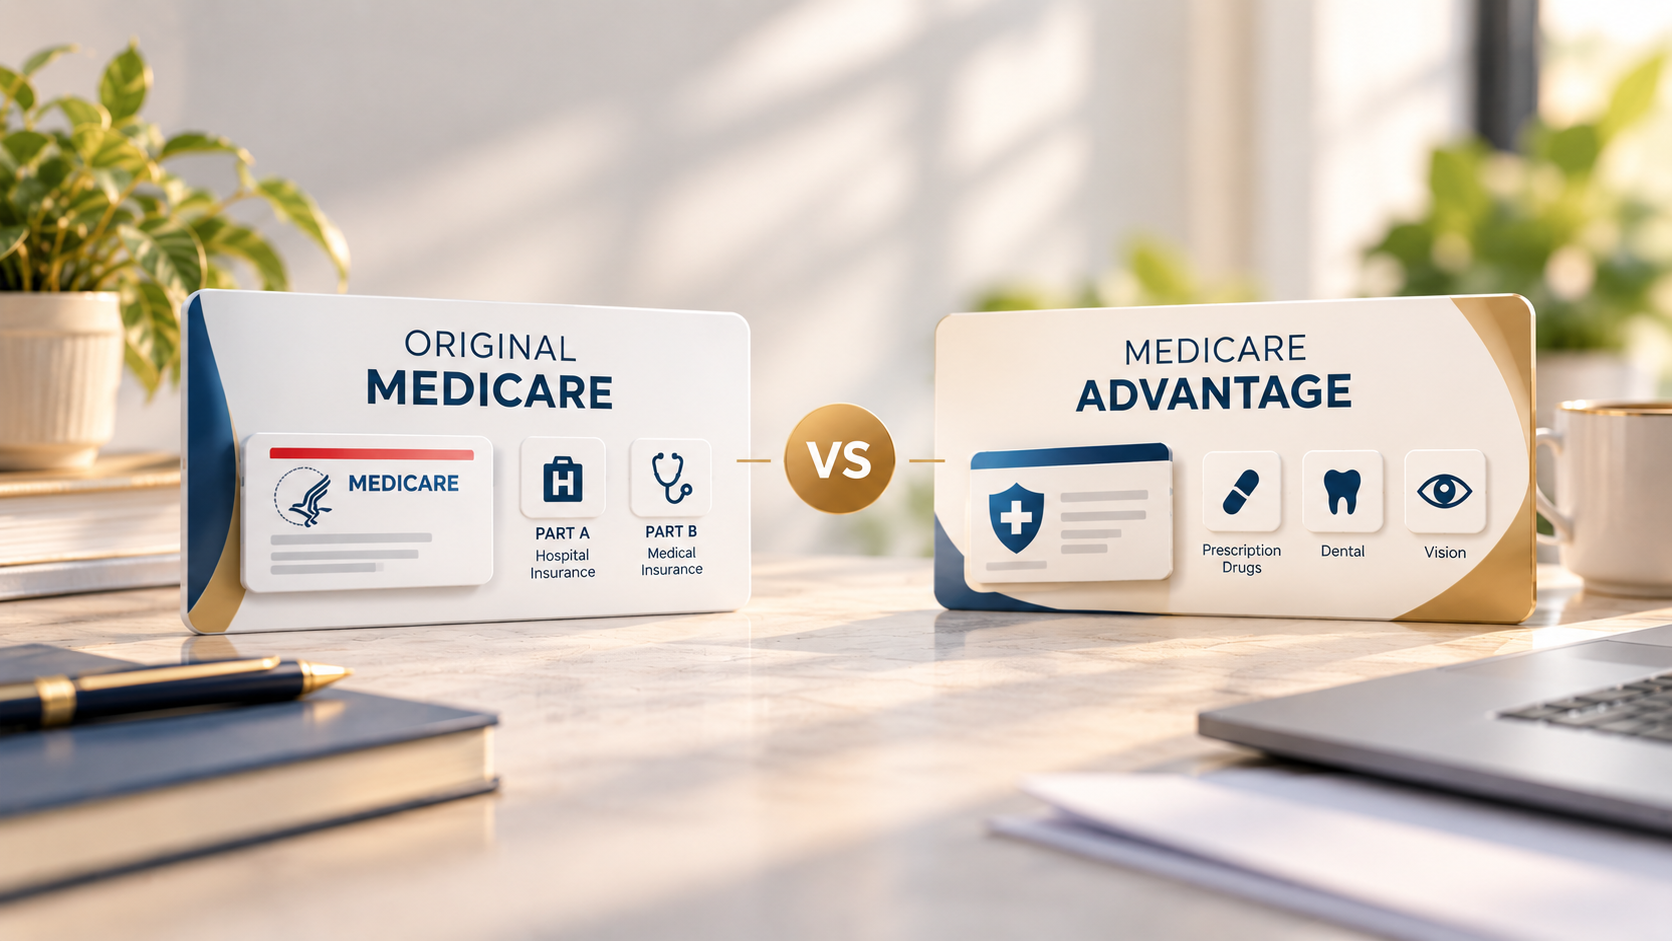
- Original Medicare (Parts A & B) with Medigap: While Medigap is renewable, premiums can increase. You can add or change a Part D plan. Switching to Medicare Advantage during AEP is possible, but dropping Medigap and re-enrolling later often involves medical underwriting.
- Changes in Health or Finances: New conditions, doctors, medications, or income shifts (impacting IRMAA) all warrant a review.
Reviewing ensures you don't miss potential savings or improved benefits.
What Changes Can You Make During AEP?
AEP offers significant flexibility to adjust your Medicare coverage.
Switching Medicare Advantage Plans
If you have a Medicare Advantage Plan (Part C), you can:
- Switch to a different Medicare Advantage Plan.
- Switch from your Medicare Advantage Plan back to Original Medicare (Parts A & B). If so, you can also enroll in a stand-alone Medicare Part D plan. Adding Medigap may require medical underwriting in most states.
Enrolling in a Medicare Advantage Plan
If you have Original Medicare (Parts A & B), you can:
- Switch to a Medicare Advantage Plan (Part C). This plan then provides your Part A and Part B benefits, often including drug coverage (MAPD).
- Enroll in a stand-alone Medicare Part D Plan if you don't have one.
Changing Prescription Drug Plans (Part D)
For those with Original Medicare, Medigap, or non-drug-inclusive MA plans, you can:
- Enroll in a Part D Plan for the first time.
- Switch from one Part D Plan to another.
- Drop your Part D Plan (generally not advised without credible alternative coverage).
AEP is primarily for Medicare Advantage and Part D adjustments. Medigap changes typically involve medical underwriting.
How to Prepare for Open Enrollment: Your Step-by-Step Guide
Preparing for Open Enrollment proactively makes the review smoother.
- Gather Current Plan Information:Locate your plan's Annual Notice of Change (ANOC) and Evidence of Coverage (EOC), usually mailed in September. The ANOC summarizes upcoming changes.
- Keep your Medicare card handy.
- List All Current Medications:Write down every prescription drug (dosage, frequency) and any regularly used OTC medications. Note your preferred pharmacy.
- Review Healthcare Needs:Consider new diagnoses or anticipated specialist visits. List all current doctors and preferred hospitals. Confirm their network status.
- Assess Your Budget:Review past year's out-of-pocket costs. Consider your comfort with different cost structures. Research eligibility for Extra Help or Medicare Savings Programs if income changed.
- Start Researching and Comparing Plans:After Oct 15, use Medicare.gov's Plan Finder or connect with a licensed independent agent. Compare plans based on doctors, prescriptions, and total estimated annual costs.
- Don't Procrastinate:Allow ample time to review, ask questions, and enroll before December 7th.
Key Factors to Consider When Reviewing Plans
When comparing Medicare plans, look beyond premiums. A comprehensive review examines critical components affecting your care and costs.
- Premiums: Your monthly payment. Consider it with other costs; $0 premium doesn't mean free healthcare.
- Deductibles, Copayments, Coinsurance: Your out-of-pocket contributions for services and drugs.
- Out-of-Pocket Maximum (Medicare Advantage): The most you'll pay for covered Part A/B services annually. A vital financial safety net.
- Provider Network:HMOs: Often require a PCP and referrals; limited out-of-network coverage.
- PPOs: More flexibility, typically no referrals needed, some out-of-network coverage (higher cost).
- Always confirm your doctors and hospitals are in-network.
- Prescription Drug Formulary: The plan's covered drug list. Check if your medications are covered, their cost tier, and any restrictions. Compare pharmacy networks.
- Extra Benefits (Medicare Advantage): Many plans offer dental, vision, hearing, fitness, or OTC allowances. Evaluate their true value to you.
Understanding Annual Changes and Your Medicare Costs
Beyond plan-specific benefits, be aware of broader Medicare cost changes set annually by CMS. These impact your overall budget.
Medicare Part B Premiums and Deductibles
CMS announces these annually. Even with a $0 Medicare Advantage premium, you'll still pay your Part B premium.
Income-Related Monthly Adjustment Amount (IRMAA)
If your modified adjusted gross income exceeds annual CMS thresholds, you'll pay an IRMAA for both Part B and Part D premiums. This is based on income from two years prior; appeals are possible for significant decreases.
Part D Deductibles and Initial Coverage Limits
CMS annually sets the standard Part D deductible and initial coverage limit, determining your drug costs before plan coverage and the coverage gap.
Maximum Out-of-Pocket (MOOP) Limit for Medicare Advantage
CMS sets an annual MOOP limit for MA plans. Plans cannot exceed this for covered Part A and B services, offering crucial financial protection.
Staying informed about these cost adjustments helps you budget effectively.
Common Mistakes to Avoid During Open Enrollment
Navigating Medicare is complex; avoid these common AEP pitfalls.
- Assuming No Plan Changes: Always review your ANOC and compare options.
- Focusing Only on Premiums: Consider total estimated annual costs, not just a low premium.
- Ignoring Prescription Drugs: Failing to check formulary coverage for medications can lead to significant expenses.
- Not Checking Provider Networks: Confirm your preferred doctors are in-network for any new plan.
- Waiting Until the Last Minute: Don't procrastinate. Allow ample time before December 7th.
- Falling for High-Pressure Sales: Be wary of unsolicited calls. Legitimate agents offer unbiased information without pressure.
- Not Seeking Expert Help: The Medicare landscape is overwhelming. A licensed, independent agent offers free, personalized guidance, comparing multiple carriers.
Frequently Asked Questions
When exactly is Medicare Open Enrollment?
Medicare Open Enrollment runs from October 15th through December 7th each year. Changes take effect on January 1st.
What if I don't make any changes during Open Enrollment?
Your current plan generally renews, but its benefits, costs, and formulary can change annually. It might no longer be your best fit.
Can I change my Medigap (Medicare Supplement) plan during Open Enrollment?
AEP focuses on Medicare Advantage and Part D. Medigap changes typically require medical underwriting outside specific guaranteed issue periods.
What's the difference between Medicare Open Enrollment and the Medicare Advantage Open Enrollment Period?
AEP (Oct 15 - Dec 7) is for most MA and Part D changes. MA OEP (Jan 1 - Mar 31) allows those already in an MA plan to switch to another MA plan or back to Original Medicare (with Part D). You cannot switch from Original Medicare to MA during MA OEP.
Secure Your Best Medicare Coverage for the Year Ahead
Medicare Open Enrollment is your annual chance to take control of your healthcare and ensure your coverage aligns with your life. The information and options can be overwhelming, but you don't have to navigate it alone.
As Jeanelle Regal, a licensed, independent insurance agent listed on Medicare Agents Helpline, my purpose is to simplify this process. We work with many top-rated insurance carriers, offering unbiased comparisons to help you explore all available plans in your area, completely free of charge. We provide clear, accurate information and personalized recommendations.
Don't let the countdown to Medicare Open Enrollment pass by without a thorough review. Whether you're turning 65, already on Medicare, or helping a loved one, we offer the expert guidance you need. Contact us today for a free consultation. Let's find a Medicare plan that gives you confidence and peace of mind.